

There is a particular kind of wedding planning optimism that makes a five-figure floral installation feel completely reasonable. You see the venue, imagine the candlelit tables, add the live band to your Pinterest board, and suddenly your original budget looks more like a polite suggestion than an actual limit.
Then comes the question nobody wants to ask while choosing their reception entrance song: What if we just borrow the difference?
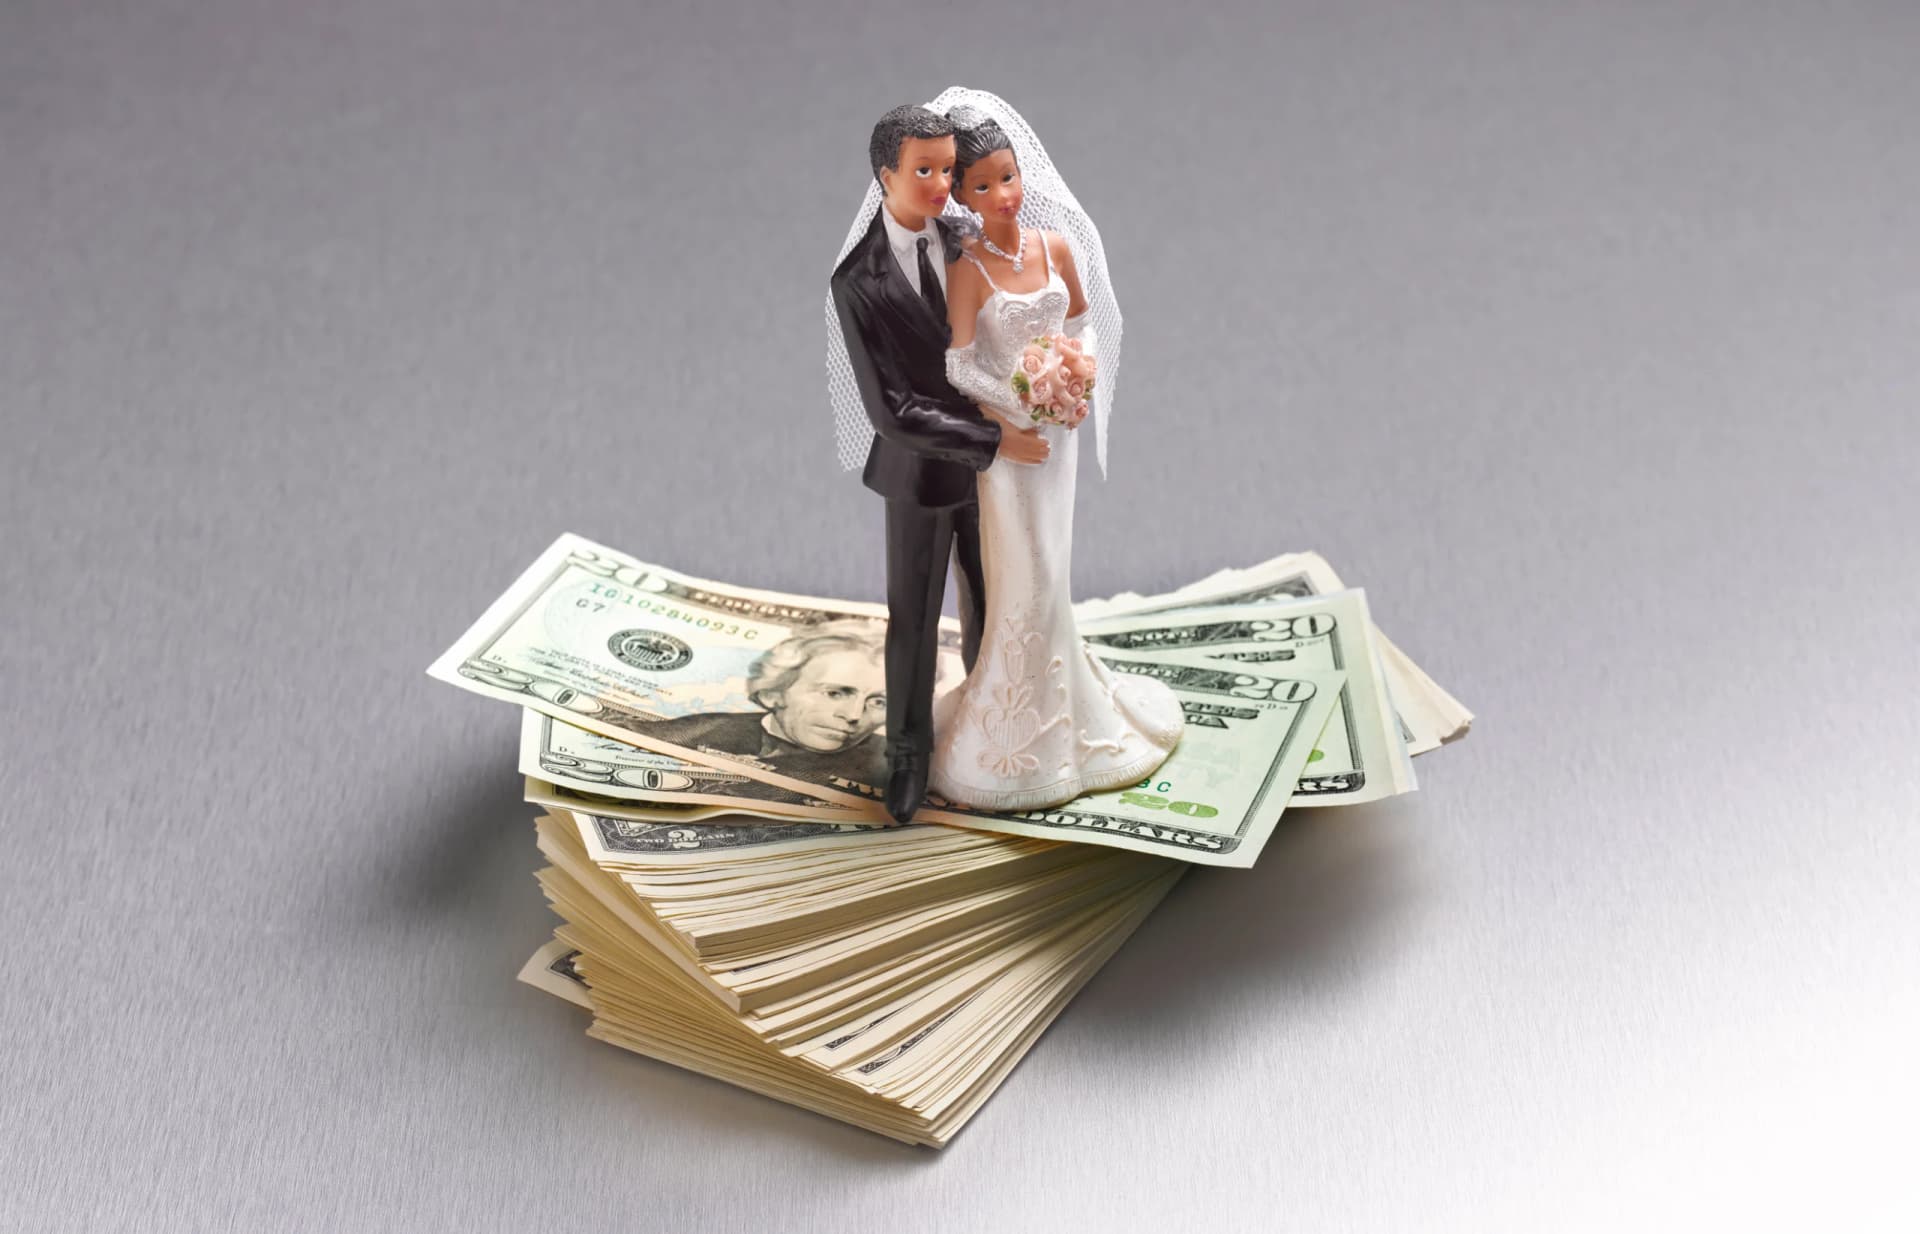
Taking out a personal loan or putting wedding expenses on a credit card can make an expensive celebration possible, but it also means paying for that celebration after the guests have gone home. And while a wedding is a meaningful milestone, our stance is that you should not go into debt simply to afford a more extravagant version of it.
The good news is that creating a memorable wedding does not have to mean sacrificing every detail you love. A thoughtful budget, the right venue and a team that understands your priorities can make a significant difference. Wedded Concierge helps couples connect with trusted venues, suppliers and wedding professionals who can work with their celebration, destination and personal style.

Wedding debt is not exactly unusual. In a LendingTree survey, 67% of newlyweds said they took on debt to pay for their wedding, while 24% reported that they were still paying it off. The survey also found that some borrowers expected to need a year or longer to clear their remaining balances. These figures reflect a US survey, rather than a universal picture of couples worldwide, but they illustrate how easily wedding expenses can follow newlyweds into married life.
The problem is not that couples want a beautiful wedding. It is that the industry can make certain expenses feel essential when they are actually optional. A larger guest list, an additional outfit, a more elaborate floral installation or a premium entertainment package can each seem manageable in isolation. Add them together, and the final bill can become much harder to justify.
Borrowing fills the gap between what you want to spend and what you can afford today. It does not make that gap disappear.

Imagine paying monthly installments for a reception that lasted six hours. The flowers have wilted, the cake has been eaten, and your honeymoon photos are already on Instagram, but the payments are still arriving.
With a loan, you repay the amount borrowed plus interest and potentially fees. With a credit card, carrying a balance can make the original purchase more expensive over time. The exact cost depends on the interest rate, repayment term, fees and how quickly you pay off the balance.
That money could otherwise contribute to a home deposit, an emergency fund, travel, further education or simply a little breathing room while adjusting to married life. Financial guidance from Wells Fargo similarly cautions against carrying long-term debt for a wedding, particularly when it means paying for the event long after it has happened.
The question is not whether your wedding is worth celebrating. It is whether the extra expense is worth delaying other goals that matter to both of you.

There can be exceptions, but the circumstances matter.
A manageable, short-term borrowing arrangement may be less risky for a couple with stable income, a clear repayment plan and enough financial flexibility to cover essential expenses. For example, a couple might consider a small loan to bridge a temporary cash-flow gap when a payment is due before an already-confirmed source of funds arrives.
That is very different from borrowing thousands because the wedding you want costs substantially more than you can realistically afford.
Before taking out a loan, ask yourselves:
Can we comfortably make the repayments after accounting for rent or mortgage payments, bills, existing debt and savings?
Have we calculated the total repayment amount, including interest and fees?
What happens if one of us loses income or an unexpected expense comes up?
Are we borrowing for something genuinely important to us, or because we feel pressured to meet other people's expectations?
If the repayments depend on everything going perfectly, the plan probably needs revisiting. And if you need a credit card balance to keep rolling over because you cannot afford to pay it down, that is a warning sign rather than a clever budgeting trick.

Here is where we would put the energy instead: decide what matters most, then build the celebration around those priorities.
If an incredible meal is non-negotiable, consider a smaller guest list before compromising on the food. If the venue is your priority, simplify the flowers or choose a naturally beautiful setting that needs less decoration. If you want a packed dance floor, invest in entertainment rather than adding reception extras you barely care about.
A few other ways to keep costs in check:
Set a budget based on available money. Start with your savings, confirmed contributions and realistic monthly savings before booking suppliers. Do not build the budget around a loan you have not yet figured out how to repay.
Give yourselves more time. A longer engagement can provide more time to save and spread out payments without relying on expensive borrowing.
Be selective with the guest list. Guest count affects catering, seating, stationery and often venue costs. Inviting fewer people can create room in the budget for the details that matter most.
Read supplier contracts carefully. Understand deposits, payment schedules, cancellation terms and what happens if plans change. A payment plan is not necessarily debt-free, so know exactly what you are committing to.
Avoid comparing your wedding to someone else's. You do not know how another couple paid for their celebration, whether their families contributed or what trade-offs they made behind the scenes.

A wedding can be worth saving for, planning carefully and spending meaningfully on. But there is a difference between investing in a celebration you can afford and borrowing to create a version of it that stretches you beyond your means.
You do not need to begin married life with a financial hangover to prove that your wedding was special. The goal is not to have the cheapest wedding possible, either. It is to spend intentionally on the things you value without making your future selves pay for choices made under pressure.
The best wedding budget is one that lets you enjoy the day and still feel good about your finances when the bills arrive. Because the celebration lasts a day, but the financial decisions you make around it can follow you for much longer.
Search real weddings, venues and vendors from around the world.
Search Wedded Wonderland